Vip Access Does My Homeowners Insurance Cover Roof Leaks

So, Your Roof's Leaking, Eh? Let's Dive into the Insurance Muddle!
Alright, picture this: You're chillin' at home, binge-watching your favorite show, when suddenly, a droplet of water lands on your nose. You look up, and there it is - a leaky roof, staring down at you like a guilty puppy. Now, you're probably wondering, "Does my homeowners insurance cover this little waterfall?" Well, grab a cup of coffee, 'cause we're about to find out!
First Things First: What's the Deal with Homeowners Insurance?
Homeowners insurance is like that overprotective friend who's always got your back. It's there to help you out when life throws a curveball, like a leaky roof, a burst pipe, or even a break-in. But here's the thing - it's not a one-size-fits-all situation. Policies can vary, and some might cover roof leaks, while others might leave you high and dry (pun intended).
Now, you might be thinking, "But I pay good money for this insurance! They should cover everything!" Well, hold onto your hats, 'cause we're about to dive into the world of deductibles, exclusions, and endorsements. It's like trying to navigate a buffet line at an all-you-can-eat restaurant - there's a lot to choose from, but you've gotta know what you're looking for!
Must Read
When It Rains, It Pours: Understanding Roof Leaks
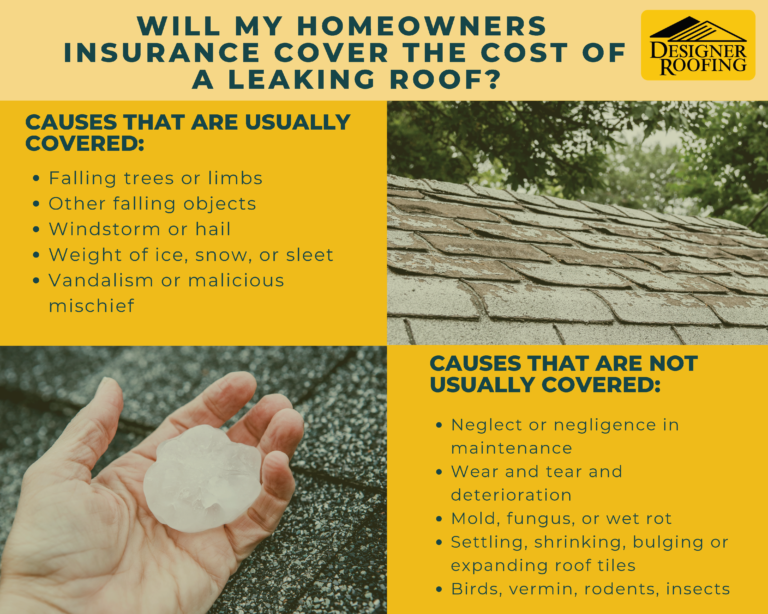
Roof leaks can happen for all sorts of reasons - age, poor installation, or even those pesky squirrels nesting in your attic. But here's a fun fact for you: Did you know that most homeowners insurance policies do cover sudden and accidental water damage? That's right, folks! If a tree falls on your roof during a storm and causes a leak, your insurance might just foot the bill.
However, there's a catch (isn't there always?). If the leak is due to gradual damage, like a slow leak that's been dripping for months, your insurance might not cover it. That's because gradual damage is often seen as a maintenance issue - something that you, as the homeowner, should have noticed and fixed before it became a big problem.
Now, you might be wondering, "How am I supposed to know if my leak is sudden and accidental or gradual damage?" Well, that's where your trusty old friend, the inspection, comes in. Regular roof inspections can help you catch leaks early and avoid any nasty surprises when it comes time to file a claim.

The Fine Print: Deductibles, Exclusions, and Endorsements, Oh My!
Alright, so you've got a sudden and accidental leak, and you're pretty sure your insurance will cover it. But before you start planning that dream vacation with your newfound cash, there are a few things you need to consider.
First up, we've got deductibles. That's the amount you have to pay out of pocket before your insurance kicks in. Deductibles can vary, so it's important to know what yours is. For example, if your deductible is $1,000 and the repair costs $2,500, you'll have to shell out $1,000, and your insurance will cover the remaining $1,500.
Next, we've got exclusions. These are the things that your insurance won't cover. For example, some policies might exclude damage caused by flooding, earthquakes, or even certain types of roofing materials. So, it's important to read the fine print and make sure you're not caught off guard by any exclusions.
Finally, we've got endorsements. These are like little add-ons to your policy that can help cover things that aren't typically included. For example, you might be able to add an endorsement to cover damage caused by mold or mildew. Just remember, these endorsements usually come at an additional cost.
So, Should You File a Claim or Not?
Alright, so you've got a leak, you've checked your policy, and you're still not sure what to do. Should you file a claim or not? Well, that depends on a few factors.
First, consider the cost of the repair. If the repair is going to cost more than your deductible, it might be worth filing a claim. However, if the repair is relatively inexpensive, you might want to pay for it out of pocket to avoid a potential increase in your premium.
Next, consider your claims history. If you've filed a lot of claims in the past, your insurance company might start to see you as a risk, and they might even decide not to renew your policy. So, it's important to weigh the pros and cons before filing a claim.
Finally, consider the cause of the leak. If the leak is due to something that's not covered by your policy, like gradual damage or an exclusion, it's probably not worth filing a claim.
The Bottom Line: Communication is Key
So, there you have it - a crash course in homeowners insurance and roof leaks. The moral of the story? Communication is key. Make sure you understand what your policy covers and what it doesn't. Talk to your insurance agent, ask questions, and don't be afraid to negotiate. After all, knowledge is power, and the more you know, the better equipped you'll be to handle whatever life throws your way - even if it's just a leaky roof.
And remember, folks - if all else fails, you can always blame it on the squirrels. They're sneaky little critters, and nobody would blame you for not noticing their handiwork. Just don't tell them we said that. They've got enough on their plate as it is.