Does Homeowners Insurance Cover Pipe Leaks Premium Link Free
So, you've got a leaky pipe, huh? Welcome to the club, my friend. You're now a member of the 'Drip, Drip, Drip' society, where the only thing more abundant than water is the 'I should've fixed that yesterday' regrets. But fear not, for today we're going to dive into the murky depths of homeowners insurance and find out if it's going to bail you out of this wet mess.
First things first, let's talk about what homeowners insurance doesn't cover.
Imagine homeowners insurance as a picky eater at a buffet. It'll gobble up stuff like fire, theft, and alien invasions (okay, maybe not that last one, but a guy can dream, right?), but it's got a few items on its 'do not touch' list. And guess what's on that list? Yep, those pesky pipe leaks.
Now, before you start planning a protest march with your leaky faucet as the mascot, let me stop you right there. It's not all doom and gloom. See, homeowners insurance is like that friend who's always got your back, but sometimes they need a little nudge to step in. And that, my friend, is where the fine print comes in.
Must Read
So, when does homeowners insurance cover pipe leaks?
Alright, grab a pen and paper, because we're about to get into some serious insurance jargon. Ready? Here we go: sudden and accidental water damage. Say that five times fast, I dare you.
Now, what does that mean in plain English? Well, imagine you're walking down the street, and suddenly, a pipe bursts like a watery piñata. That's sudden. And if your carpet looks like it's been through a monsoon, that's accidental. In that case, your homeowners insurance might just pick up the tab.
But here's where it gets tricky. If that leak has been happening for a while, and you've been ignoring it like an annoying neighbor, well, that's not sudden. And if it's not sudden, your insurance company might turn into the world's worst party guest and refuse to pay the bill.
Think of it like this: if your pipe was a car, and it suddenly started leaking oil all over the driveway, that's sudden and accidental. But if you've been ignoring the 'check engine' light for months, and the car finally gives up the ghost, that's not sudden. It's more like 'eventual' or 'inevitable'. And no one wants to insure 'inevitable'.
But what about those sneaky, hidden leaks?
You know the ones. They lurk in the shadows, silently causing chaos behind your walls. They're like the Voldemort of home repairs - we do not speak of them. But what if one of these sneaky suckers decides to make an appearance? Will your insurance company come to the rescue?
Well, it depends. Some policies might cover hidden leaks if they're sudden and accidental. But others might have a time limit on when you can make a claim after discovering the leak. It's like that game 'I Spy', but with less fun and more potential for financial ruin.
And here's a fun fact for you: some insurance companies might cover hidden leaks if they're caused by something sudden, like a burst pipe. But if the leak is due to something gradual, like a slow drip over time, they might not cover it. It's like they're playing favorites with your pipes. 'Oh, you burst suddenly? We love you! But you, slow drip... you're on your own.'
So, what can you do to protect yourself from leaky pipe woes?
First things first, don't be that guy who ignores the signs of a leaky pipe. If you see water where it shouldn't be, or hear the drip, drip, drip of doom, don't wait. Get it fixed, and keep the receipts. That way, if the worst happens, you've got proof that you were trying to be a responsible homeowner.
Next up, give your insurance company a call. Ask them about your policy's coverage for water damage. Find out what's sudden and accidental, and what's not. And while you're at it, ask about any exclusions or limitations. Knowledge is power, my friend, and you want to be armed with as much of it as possible.
And here's a pro tip for you: consider getting a home warranty. It's like a safety net for all those little home repairs that can add up to a big ol' bill. Some home warranties cover water damage, and some even cover regular maintenance. It's like having a personal handyman on retainer. Just don't tell your actual handyman I said that.
But what if you're already knee-deep in water damage?
Well, first things first, don't panic. I know that's easier said than done when you're staring at a lake in your living room, but bear with me. Grab your phone and take some pictures. Document the damage, because you're going to need that for your insurance claim.
Then, give your insurance company a call. They'll guide you through the claim process, and they might even be able to recommend a water damage restoration company. Just remember to keep receipts for any emergency repairs you have to make. You might be able to get reimbursed for them later.
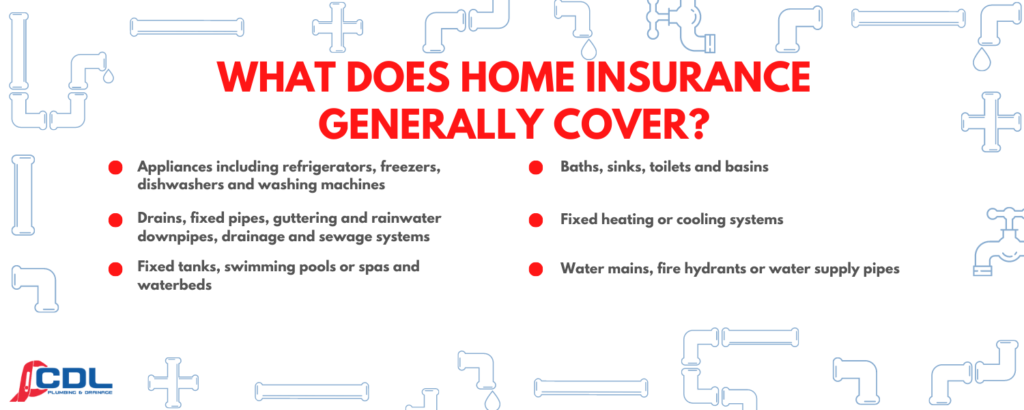
And here's another fun fact for you: some insurance policies have a 'betterment' clause. That means if you've got old pipes that finally give out, and you replace them with new ones, your insurance company might only pay for the cost of the old pipes. It's like they're saying, 'You should've upgraded ages ago, so we're not going to pay for the upgrade now.' Thanks, insurance company. Way to kick a guy when he's down.
So, what have we learned today?
Well, we've learned that homeowners insurance is a fickle beast when it comes to pipe leaks. It's like trying to predict the weather - you never know what you're going to get. But with a little knowledge and a lot of preparation, you can be ready for whatever leaky surprise comes your way.
And remember, folks, the key to a happy home is good communication. Talk to your insurance company, talk to your plumber, and most importantly, talk to your pipes. They might not answer back, but at least you'll know you've done your part to keep the lines of communication open.
So, the next time you hear that dreaded drip, drip, drip, don't despair. You're armed with knowledge, and that's half the battle. Now go forth, and may your pipes be ever leak-free.